Account-to-account (A2A) payments move funds directly between bank accounts over real-time payment rails, without card networks. For PSPs, PayFacs and ISVs, A2A is a payment method to add to the stack they offer their merchants, alongside cards and wallets, with lower processing costs, instant settlement and new recurring use cases such as variable recurring payments.
Real-time payment systems now run in most major economies, and in several markets they carry more everyday payments than cards. This article, updated in November 2026, explains how A2A payments work, which real-time systems power them by region, what they bring to PSPs and PayFacs, the challenges of adding them, how they change card economics, what the EU Instant Payments Regulation changes, and how operators offer A2A under their own brand.
What are account-to-account payments and how do they work?
An A2A payment is a transfer initiated from the payer's bank account to the payee's bank account. At checkout, the customer usually approves it in a banking app, by scanning a QR code or by being redirected to their bank, and the funds move over an instant payment system within seconds.
In Europe, these payments run on SEPA Instant Credit Transfer. The European Payments Initiative's Wero is now taking A2A to online and in-store checkout: launched for peer-to-peer payments in 2024, it is rolling out to e-commerce country by country, starting with Germany and Belgium, with the Netherlands to follow. The instant payments article covers the European picture in detail.
Which real-time payment systems power A2A payments by region?
Each region has its own reference system, often built or mandated by the central bank:

- Brazil, Pix: launched by the Central Bank of Brazil in November 2020, available 24/7 and now the country's most used payment method.
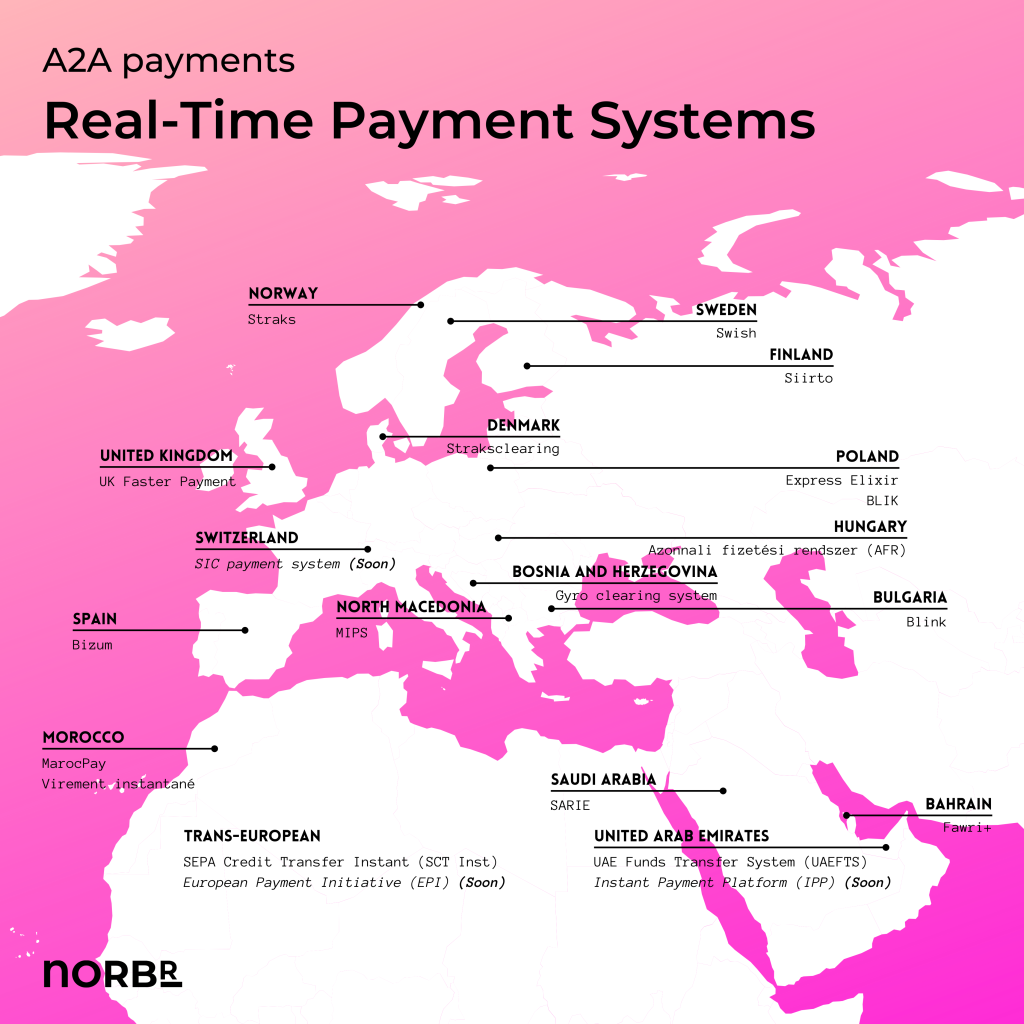
- United Kingdom, Faster Payments: live since 2008, the base for open banking payments and variable recurring payments.
- United Arab Emirates, Instant Payment Platform: launched in 2023 by the Central Bank of the UAE as part of its financial infrastructure program.
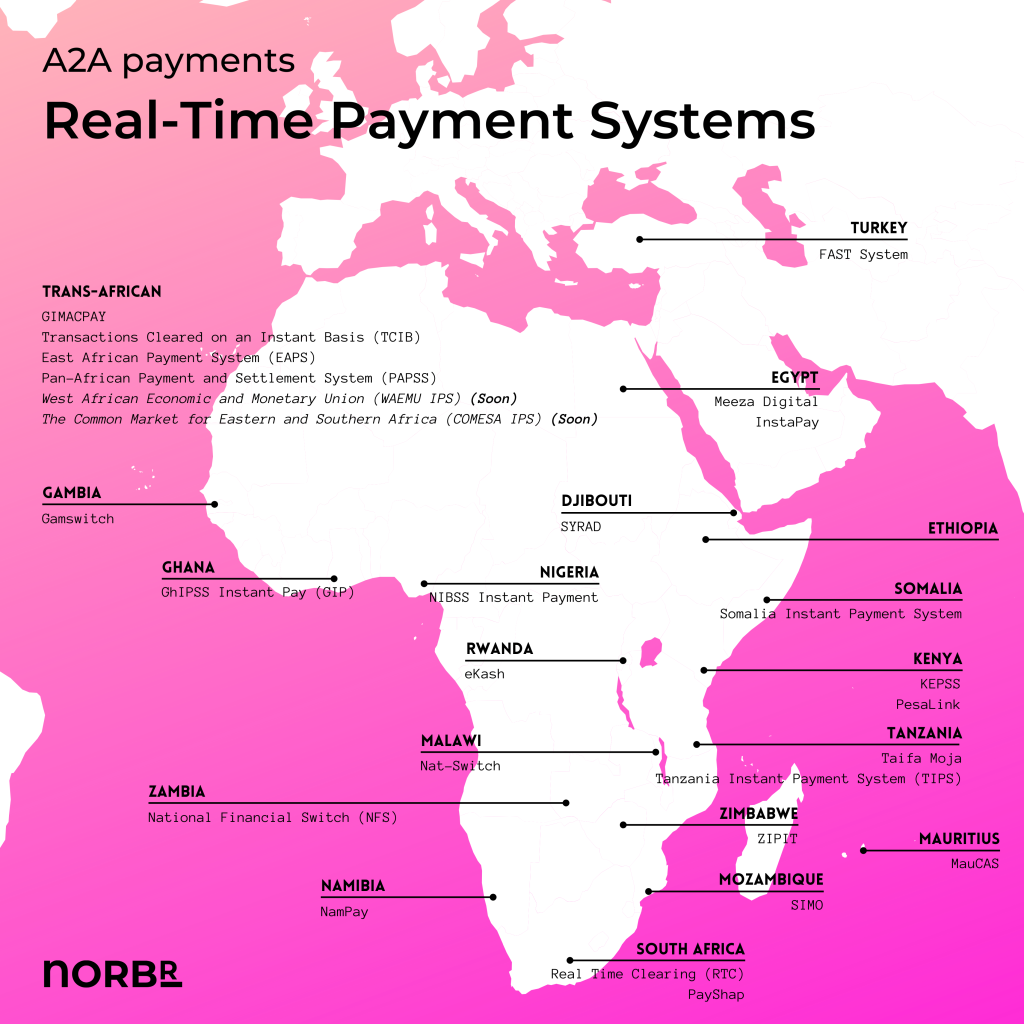
- Nigeria, NIBSS Instant Payment: live since 2011 across the country's banking network.
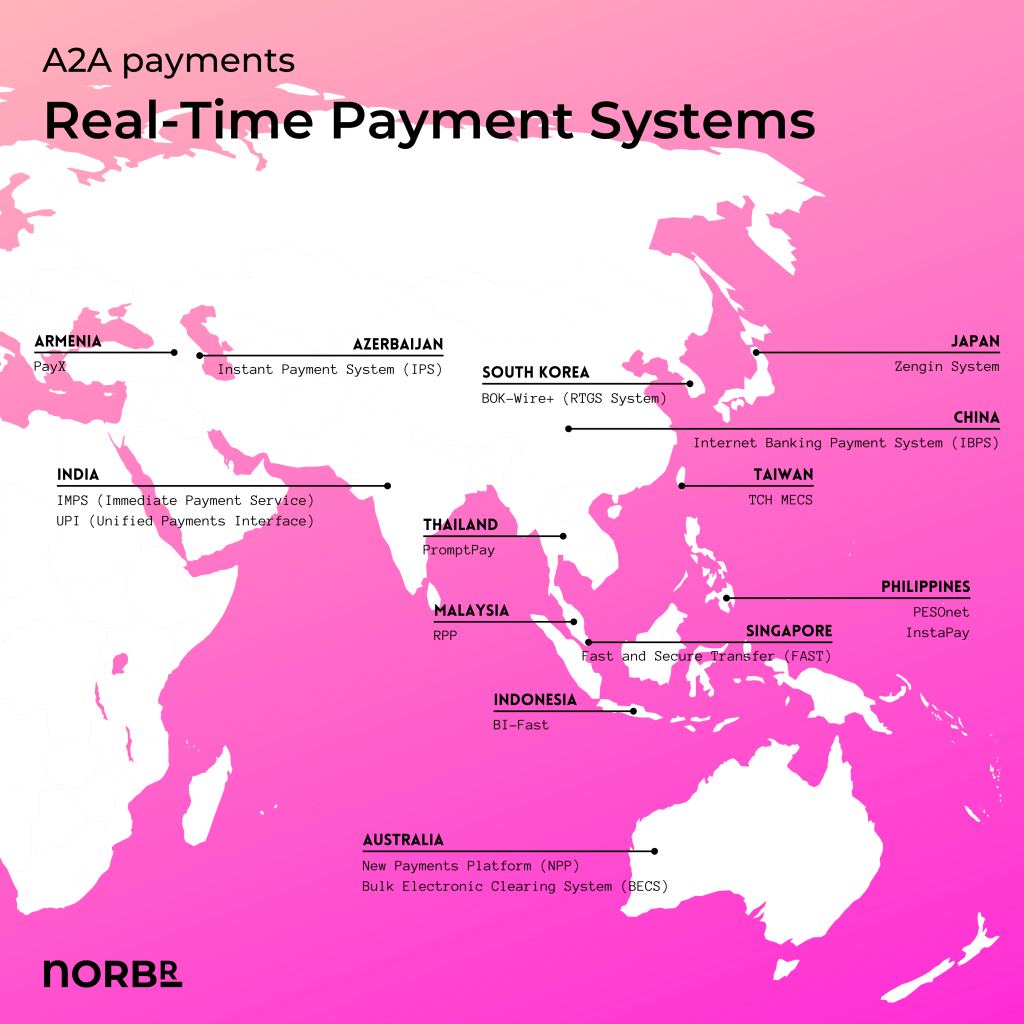
- India, UPI: launched in 2016. According to NPCI data published in September 2026, UPI processed a record 24.51 billion transactions in August 2026, 22 percent more than a year earlier.
The #PayWorldTour guides describe the local A2A methods market by market.
What are the benefits of A2A payments for PSPs and PayFacs?
For the operators serving merchants, A2A adds a method with a different cost and risk profile from cards:
- Lower processing costs, with no interchange or scheme fees, which leaves room for margin or lower merchant pricing.
- Instant settlement, which improves merchants' cash flow and can shorten the operator's own settlement cycle.
- No card chargebacks, since the customer authenticates in their bank app; disputes follow the rules of each scheme instead.
- Local reach, where A2A is the method customers prefer, as with Pix or UPI.
- New recurring use cases, such as variable recurring payments in the UK.
What are the challenges of adding A2A rails to a payment stack?
Each system has its own connection model, through banks, licensed initiation providers or local PSPs, with different APIs, refund flows and reporting. Coverage is national or regional, so an operator active in ten markets may need several providers to offer A2A everywhere.
Operations change too: refunds are new transfers rather than card reversals, reconciliation must match instant credits to orders, and consumer protection rules differ from card schemes. Each of these has to be handled once at platform level, not by every merchant.
What does the EU Instant Payments Regulation change for A2A payments?
It makes instant transfers available from almost every euro account. Under the regulation, as summarized by the European Central Bank, payment service providers in the euro area had to receive instant euro payments from January 9, 2025 and send them from October 9, 2025, at a price no higher than a standard credit transfer. From the same October date, they must offer verification of payee, which checks that the beneficiary's name matches the account before the payer confirms.
Deadlines differ for some players: payment and e-money institutions have until April 9, 2027 in the euro area, and member states outside the euro area follow a later timetable in 2027.
For operators, the result is reach. An A2A method built on SEPA Instant can now count on almost every euro-area bank account receiving funds in seconds, which removes one of the historic limits of account-based checkout. Settlement within seconds also means reconciliation has to keep pace: each instant credit has to be matched to an order as it lands, through reconciliation and settlement, and A2A methods have to sit next to cards in a checkout that presents each method where it fits.
How do A2A payments change the economics of card acceptance?
Where A2A gains share, merchants push their payment provider for cheaper alternatives to cards, and operators that cannot offer them lose pricing power. Card schemes respond with value-added services, such as network tokens that make card-on-file and recurring payments more reliable.
For PSPs and PayFacs, the result is not a replacement but a mix: cards, wallets and A2A side by side, with routing that steers each payment to the method and provider that best fits the merchant's cost and conversion goals. The payment processing fees guide covers the cost side.
How can a PSP or PayFac offer A2A payments under its own brand?
By connecting A2A providers through the same infrastructure as cards and wallets. On NORBr, A2A methods from the global payment network are activated per merchant and per market, appear in the operator's branded checkout, and follow the same reporting and reconciliation as other methods.
Routing rules decide when A2A is offered or preferred, and the payment rails page explains how operators combine card, wallet and account-based rails. The cash-to-digital article shows how A2A adoption has played out in several countries. A2A does not replace cards; it gives operators a second rail to price, route and sell.
What else do operators ask about A2A payments?
Are A2A payments covered by chargebacks?
Not by card chargebacks. The payer authorizes the transfer in their banking app, so card scheme dispute rules do not apply. Consumer protection depends on the rules of each method, and refunds are sent as new transfers that the operator's platform has to track and reconcile.
Do A2A payments work for subscriptions?
Yes, with the right mechanism. In the UK, variable recurring payments let a customer authorize a series of payments within agreed limits. In the euro area, SEPA Direct Debit remains the main recurring account-based option, while recurring features for instant methods vary by market.
How does an operator add A2A methods for its merchants?
Through providers connected to its payment infrastructure, activated per market and per merchant. On NORBr, A2A methods appear in the operator's branded checkout and follow the same routing, reporting and reconciliation as cards and wallets. Coverage depends on the providers connected for each market, and new ones are integrated on request.